Your Parent Qualifies for Help With Medicare Costs. Mississippi Just Doesn't Make It Obvious.
Every month, $202.90 disappears from your parent's Social Security check before they touch it. That's the Medicare Part B premium — and for a senior living on $1,100 to $1,500 a month in Mississippi, it's the difference between keeping the lights on and choosing which medications to skip.
Mississippi's Medicare Savings Programs exist to eliminate that deduction entirely. For the lowest-income tier — QMB — the state also wipes out every Medicare deductible, copayment, and coinsurance charge. Combined with Extra Help for prescriptions, a qualifying senior can save over $2,400 a year on Part B premiums alone, plus thousands more in medical out-of-pocket costs.
And here's what national websites won't tell you: Mississippi eliminated the asset test for all three MSP tiers. Your parent's savings account, retirement funds, and property don't count against them. But Medicare.gov still publishes the federal default limit of $9,950 — scaring away people who would qualify.
The problem isn't eligibility. It's the process.
The Mississippi DOM Navigation System
Applying for an MSP in Mississippi means navigating the Division of Medicaid — an agency where even frontline caseworkers sometimes give conflicting answers about who qualifies. One worker tells you age alone is enough. Another says you also need a disability. Both are handling the same application.
If you're an adult child helping from out of state — Tennessee, Louisiana, Alabama, or across the country — you're managing this through regional offices you can't visit, phone lines that ring out, and an online portal at Access.ms.gov that most applicants don't know exists.
In the Delta, getting to a regional DOM office can mean a three-hour round trip. On the Gulf Coast, families dealing with Medicare Advantage plans are trying to understand how a state MSP interacts with a private plan. In Jackson, the wait at the headquarters office runs long enough that people leave without filing.
The Mississippi Medicare Savings Programs & Extra Help Guide is a step-by-step navigation system built for exactly this process. It doesn't replace the Division of Medicaid or Mississippi SHIP. It organizes what they give you into a sequence you can follow — from eligibility math to approval to keeping coverage active — without calling the agency repeatedly to figure out what happens next.
What Makes This Different From Free Information
Mississippi SHIP, run through the MDHS Division of Aging and Adult Services, provides free Medicare counseling through Area Agencies on Aging. SHIP counselors can screen your parent for eligibility and answer plan comparison questions. The guide directs you there for plan choice — which Part D or Medicare Advantage plan makes sense. But SHIP counselors can't serve as your ongoing representative, can't run the income disregard math for you, can't track your application through DOM processing, can't file an appeal on your behalf, and don't provide scripts for disputing the balance bills QMB enrollees illegally receive.
Insurance broker websites publish income limit tables — then route you to a callback from a licensed agent selling a Dual Special Needs Plan. Your contact information becomes a sales lead.
This guide sells you the process once, for a flat fee. No calls. No leads. No plan recommendations. No recurring charges.
What's Inside the Guide
- The three MSP tiers decoded — what QMB, SLMB, and QI actually cover, what they don't, and how each interacts with Original Medicare and Medicare Advantage, explained without Medicaid jargon
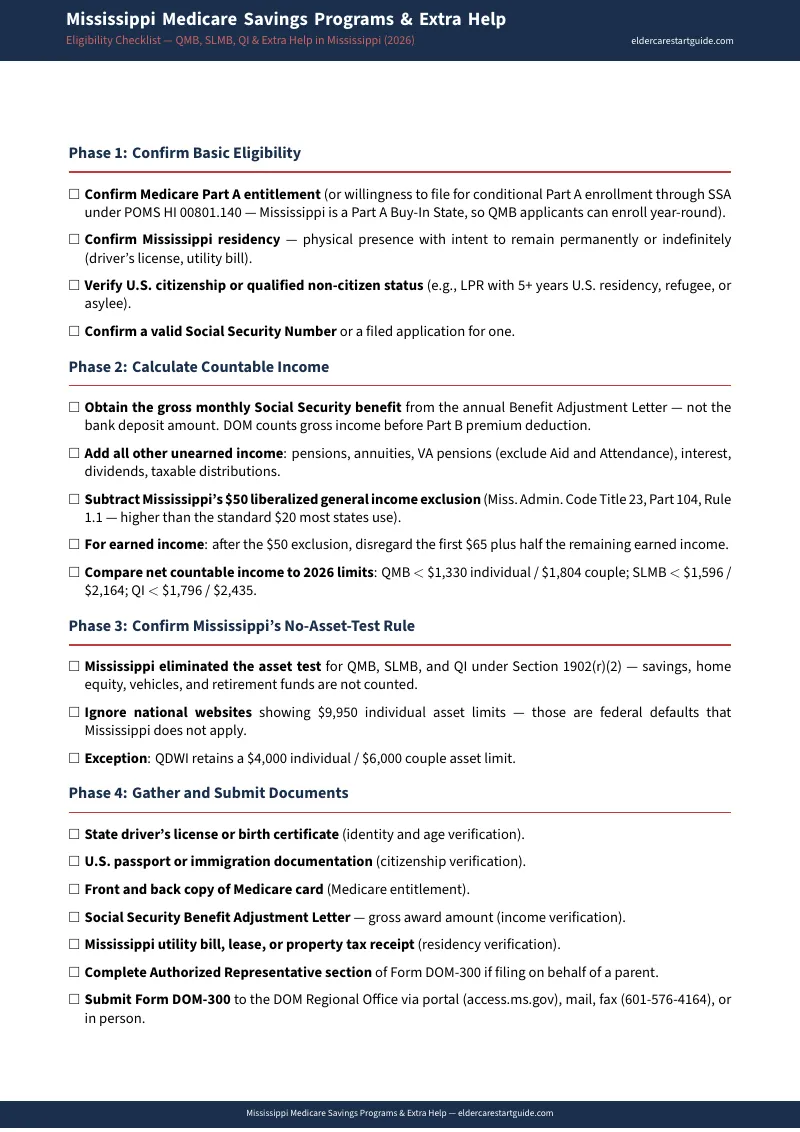
- Income eligibility math with the disregards that change the answer — Mississippi's $50 general income exclusion, the earned income disregard sequence ($65 plus half the remainder), and three worked examples showing how someone who looks over-income on paper may qualify after the math is done correctly
- No asset test — confirmed and explained — why Mississippi eliminated the resource test for all three MSPs, why national portals still display a $9,950 limit, and what this means for your parent's bank balance and retirement savings
- Application walkthrough — the Access.ms.gov online portal, paper applications, regional office visits, which form to use, and why filing with the Division of Medicaid (not MDHS) is critical to avoiding processing delays
- Decision timelines and the premium refund lag — the 45-calendar-day processing deadline (90 days when a disability determination is required), the 30-to-60-day gap after approval before SSA stops deducting Part B premiums, and how the lump-sum refund works
- Part A conditional enrollment — the path for parents without 40 work quarters who need QMB to cover their Part A premium ($565/month with fewer than 30 quarters, or $311 with 30–39 quarters, in 2026), including the Social Security step that must happen before DOM can act
- Extra Help and Part D — how MSP approval automatically triggers the Low-Income Subsidy, the $5.10/$12.65 copay caps, and why Mississippi has no general state pharmacy assistance program to fill gaps
- QMB billing protections — the federal law that prohibits providers from billing QMB enrollees for cost-sharing, and what to do when Mississippi providers send a bill anyway — including a dispute letter and phone script
- Renewals and redeterminations — how to keep coverage active, what DOM requests at renewal, and what to report between renewals to prevent a gap
- Appeals and fair hearings — how to request a hearing through the Division of Medicaid, filing deadlines, and how to keep benefits active during the appeal
- Estate recovery facts — why MSP benefits are explicitly exempt from Mississippi Medicaid Estate Recovery, and how this differs from long-term care Medicaid (which does carry recovery for beneficiaries 55 and older)
- Regional navigation — DOM regional office contacts, Jackson metro processing realities, Gulf Coast dual-eligible coordination, and Delta access barriers
- Worksheets and contacts — the Eligibility Worksheet, Application Document Checklist, Premium Refund Tracker, Agency Communication Log, Billing Dispute Log, QMB Billing Dispute Letter, Billing Protection Card, the DOM central fax number, and every regional office and counseling line you need
Who This Guide Is For
- Adult children managing a Mississippi parent's Medicare costs from anywhere — the guide covers remote application, document submission, and what happens at regional DOM offices, whether you're in-state or managing from Tennessee, Louisiana, or Alabama
- Seniors applying on their own — if the Part B premium is taking a large bite out of a fixed Social Security check and you want to know whether you qualify without calling a broker who's really a lead generator
- Families dealing with a denial, a confusing DOM notice, or a provider bill they shouldn't have received — the guide includes appeal steps, notice interpretation, and billing dispute tools
- Delta and rural families — when the nearest DOM office is an hour or more away, a structured guide that tells you exactly what to prepare before the trip prevents a second one
What This Guide Is Not
This is process navigation, not insurance advice. The guide never recommends a specific Part D, Medigap, or Medicare Advantage plan — for plan comparisons, it directs you to Mississippi SHIP at 1-844-822-4622, which is free and unbiased. It is not affiliated with CMS, SSA, the Mississippi Division of Medicaid, or any state agency. "Medicare" describes the topic; it does not brand the product.
The Guarantee
Full refund, no time limit. If the guide doesn't help, email [email protected] and we'll refund every penny. No forms, no waiting period, no questions.
Frequently Asked Questions
Will applying for an MSP let the state put a claim on my parent's house?
No. Medicare Savings Programs (QMB, SLMB, QI) pay Medicare premiums and cost-sharing only. Federal and Mississippi state law explicitly exclude MSP-only benefits from Medicaid Estate Recovery. If your parent receives only MSP benefits, their home, savings, and other property are not at risk. Long-term care Medicaid — nursing home or waiver services — is a separate program with separate rules and does carry estate recovery for beneficiaries 55 and older.
My parent has savings. Will an asset test disqualify them?
No. Mississippi completely eliminated the asset test for all three Medicare Savings Programs. There is no resource limit for QMB, SLMB, or QI in Mississippi. National portals including Medicare.gov still display the federal default of $9,950 for an individual, but Mississippi opted out of that test. Your parent's bank balance, retirement accounts, and other resources are not counted for MSP eligibility.
Is the information current for 2026?
Yes. All income limits, premium amounts, copay figures, and program rules reflect 2026 values. The guide also covers the Social Security Fairness Act's repeal of GPO and WEP, which affects income calculations for retirees who worked in public-sector jobs that didn't withhold Social Security taxes.
Frequently Asked Questions
What if the rules change after I buy?
We update the guide when the rules change. Email us any time, even years later, and we'll send you the current edition free.