Your parent's Social Security check is $202.90 lighter every month. New Hampshire can stop that deduction — but the path through DHHS is anything but clear.
Every month, Medicare takes $202.90 from your parent's Social Security check before they see a cent. On a fixed income of $1,300 or $1,400 a month, that deduction is the difference between paying the heating bill and falling behind on everything else.
New Hampshire's Medicare Savings Programs can eliminate that deduction entirely — and in the most comprehensive tier, cover deductibles, copayments, and prescription drug costs as well. The state pays Medicare directly through the Department of Health and Human Services, and your parent keeps more of their check.
The problem is figuring out how it actually works. The NH EASY portal gives you a login screen and Form 800, which mixes Medicaid expansion questions with the completely different rules for seniors. The DHHS Customer Service line routes you through hold queues that eat an afternoon. National Medicare guides publish income limits and program names that do not match what New Hampshire uses — the state calls its third tier "SLMB135" instead of "QI," and applies a $20 income disregard that no federal calculator accounts for. And if you are managing this from out of state, every step involves a time zone gap, a document you cannot upload because NH EASY deleted your unfinished session at midnight, and a form your parent cannot fill out alone.
The NH Medicare Cost Recovery System
This guide replaces scattered phone calls, conflicting web results, and guesswork with a single structured process — built for how New Hampshire's DHHS Division of Economic Stability actually runs these programs, not the generic federal version you find on Medicare.gov.
It covers the full path from checking whether your parent qualifies under New Hampshire's specific income rules through submitting a complete application, tracking the three-agency handoff that stops the premium deduction, handling billing disputes with providers, and renewing coverage year after year — including what to do when the state sends a confusing notice or an incorrect denial.
What's inside
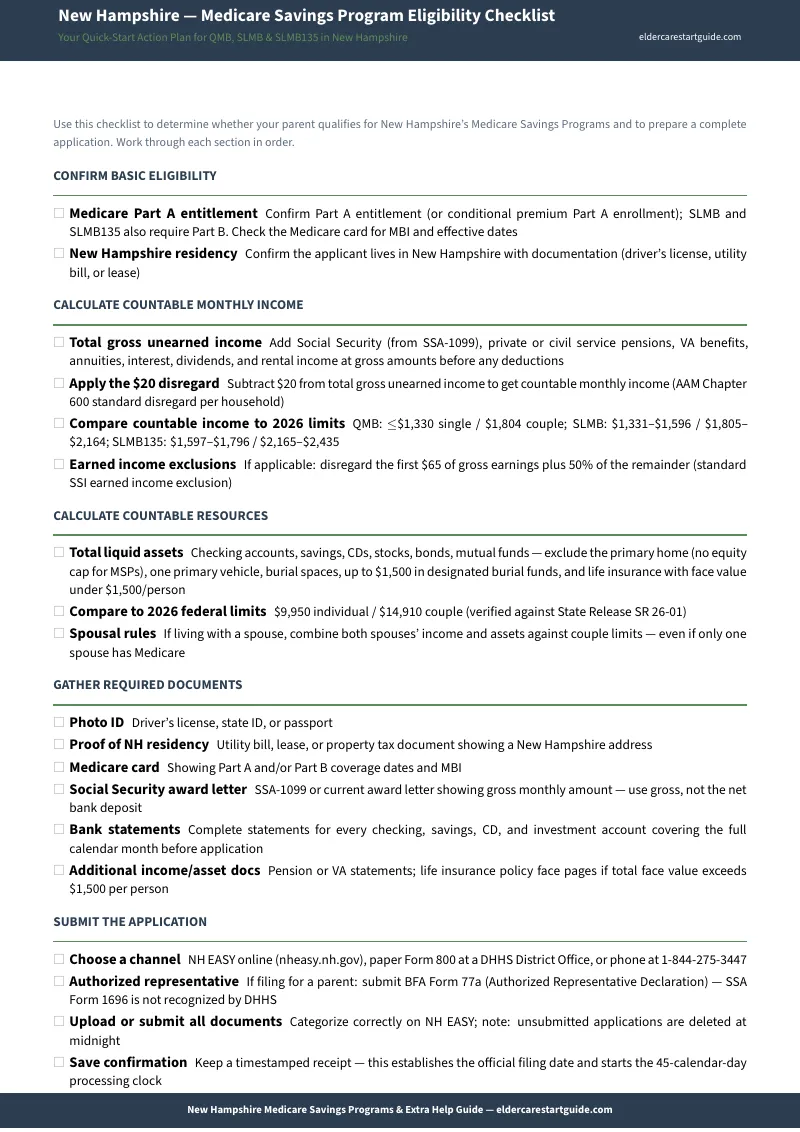
- The four-tier eligibility breakdown — QMB, SLMB, SLMB135 (QI), and QDWI explained in plain English, with the exact 2026 income and asset limits New Hampshire applies. The state uses a $20 monthly disregard on unearned income — so a parent earning $1,350/month in Social Security has countable income of $1,330, which falls at the QMB ceiling. Three worked dollar examples show how DHHS caseworkers calculate countable income, including asset exclusions that keep the family home, one vehicle, and burial funds off the table.
- NH EASY portal walkthrough and district office route — step-by-step instructions for submitting a complete application through the state's online system (nheasy.nh.gov) or a DHHS district office. Covers the five regional district offices, the Centralized Scanning Unit mailing address in Concord, and the phone, fax, and mail channels for when the portal stalls or you are applying from out of state.
- Document assembly checklist — every proof DHHS caseworkers look for (Social Security award letter, Medicare card, bank statements, pension records, life insurance policies), organized in the order Form 800 asks for them, so nothing comes back marked "verification missing" after the 10-day deadline.
- The three-agency premium timeline — after DHHS approves coverage, your parent's file moves from the state to CMS to the Social Security Administration before the premium deduction actually stops. The guide maps each handoff, the expected wait (60 to 90 days), and exactly who to call when the timeline stalls — including the specific SSA number for Part B premium adjustments.
- QMB balance billing shield — federal law prohibits Medicare providers from billing QMB enrollees for deductibles, coinsurance, and copayments. The guide explains how this protection works in practice and what to do when a doctor's office, hospital, or collection agency sends a bill anyway — including the legal citation and the steps to escalate through CMS and ServiceLink.
- Automatic Extra Help enrollment — every MSP approval triggers eligibility for Full Extra Help (the Low-Income Subsidy), capping Part D drug copays at $4.50 for generics and $11.20 for brand-name drugs in 2026. No separate application is needed. The guide explains what changes at the pharmacy and how your parent's Part D plan updates.
- Part A buy-in for QMB — if your parent does not have premium-free Part A because they lack 40 work credits, QMB can pay the Part A premium through a conditional enrollment process with SSA. The guide walks through how this works so your parent does not have to wait for a General Enrollment Period.
- WEP/GPO repeal impact — the Social Security Fairness Act eliminated the Windfall Elimination Provision and Government Pension Offset in January 2025. For former New Hampshire teachers, municipal workers, and state employees, the resulting Social Security increases and retroactive lump-sum payments can push income or assets over MSP limits. The guide explains how to handle the spend-down and when the lump sum stops counting.
- Renewal, redetermination, and appeals — how to respond to the annual renewal notice on yellow paper, what the 10-day verification deadline means, how to request an extension, what "Aid Paid Pending" does during an appeal, and how to file a fair hearing request through the DHHS Administrative Appeals Unit.
- Authorized Representative setup — how to establish legal permission to apply on your parent's behalf and communicate with DHHS caseworkers, so you can manage the process from anywhere in the country.
Who this guide is for
- Adult children helping a parent in New Hampshire navigate Medicare costs — especially if you are coordinating from out of state and need a process that works without in-person DHHS visits
- Seniors on a fixed income who want to understand whether QMB, SLMB, or QI can reduce what Medicare takes from their check each month
- Families in the North Country (Coös, Grafton, Carroll Counties) dealing with long distances to DHHS district offices and limited broadband for online submissions
- Families who received a confusing notice from DHHS — a denial, a renewal packet, or a verification request that does not explain what is actually needed
- Anyone who has been told their parent "doesn't qualify" based on income but has not had the $20 unearned income disregard and asset exclusions properly applied
Why free resources leave the hard parts unsolved
ServiceLink (New Hampshire's SHIP program) provides free, unbiased Medicare counseling, and their counselors are excellent at eligibility screening. But ServiceLink does not assemble your document packet, walk you through the NH EASY upload process, track the three-agency handoff between DHHS and Social Security, or help you decode a redetermination notice that arrives on yellow paper without clear instructions. That is not a failing of ServiceLink — it is outside their scope. And during Open Enrollment and post-PHE renewal periods, appointment wait times stretch to several weeks.
Medicare.gov and BenefitsCheckUp run federal eligibility calculators that publish standard FPL percentages without accounting for New Hampshire's $20 income disregard. National Medicare books on Amazon explain the federal program without mentioning NH EASY, Form 800, SLMB135, or how the Division of Economic Stability processes verifications in each region. If your parent earns $1,350/month and you check a national calculator, you see "over income" when they actually qualify.
An elder law attorney can handle complex Medicaid planning, but retainers in New Hampshire start at $2,500 — sensible for nursing home asset protection, not for getting a $202.90/month premium covered.
This guide fills the space between the free screening and the expensive legal consultation: a structured, New Hampshire-specific process you can follow on your own.
Satisfaction guarantee
Full refund, no time limit. If the guide does not help, email [email protected] and we will refund it.
Independent educational guide. Not affiliated with CMS, the Social Security Administration, or the New Hampshire Department of Health and Human Services. All eligibility thresholds reflect official 2026 federal and state standards.
Frequently Asked Questions
What if the rules change after I buy?
We update the guide when the rules change. Email us any time, even years later, and we'll send you the current edition free.