Hundreds of dollars a month in Medicare surcharges — based on income you no longer earn
You retired. Your spouse died. Your pension was restructured. And now a notice from Social Security says your Medicare Part B and Part D premiums are hundreds of dollars higher than they should be — because SSA is still using tax data from two years ago, when your income looked entirely different.
The surcharge is called IRMAA — the Income-Related Monthly Adjustment Amount. It applies to Medicare beneficiaries with Part B, Part D prescription drug coverage, or both, whose Modified Adjusted Gross Income exceeds the applicable threshold. For 2026, those thresholds are based on your 2024 tax return: above $109,000 for single filers, above $218,000 for joint filers. If you were working, running a business, or receiving a one-time payout in 2024, the IRMAA surcharge can add $200 to $400 a month to your premiums — costs that no longer match your actual financial situation.
What the notice doesn't make clear: when a qualifying life-changing event has reduced your income, you can ask Social Security for a new initial determination using Form SSA-44. If your event qualifies and your projected income falls into a lower bracket, SSA adjusts your premiums and refunds the months you overpaid.
The Proof-Perfect Filing System
The SSA-44 PDF has four form pages followed by four pages of instructions. The process behind it is not. SSA recognizes exactly eight life-changing events, each with specific evidence requirements drawn from the Program Operations Manual System. The form asks you to estimate your Modified Adjusted Gross Income by mapping IRS Form 1040 lines to SSA's income fields — a step where most errors happen; the instructions identify Lines 11 and 2a, but don't work through a multi-year estimate for you. When both spouses need an IRMAA change, one SSA-44 doesn't cover both. For Part B premiums withheld from benefits, SSA may pay a refund as a prior-month accrual or current-amount check; for direct CMS bills, overpayments apply first to past-due balances, then to Part B and Part A, and lastly to Part D IRMAA where applicable.
The Proof-Perfect Filing System replaces the guesswork with a structured sequence: confirm that your event qualifies, gather the evidence SSA lists, estimate your income correctly on the form, and track the outcome after you file. If you lack a listed document, SSA may accept another type in some cases. It's the organized packet you bring to the field office or upload through your my Social Security account — built so the submission is complete the first time.
What's inside
- The eight qualifying life-changing events, mapped to their evidence — not just a list, but a cross-reference of each event (retirement, death of a spouse, work reduction, divorce, loss of income-producing property, loss of pension, marriage, employer settlement) with the primary and secondary evidence SSA lists under POMS HI 01120.001–01120.043. The guide explains work-stoppage evidence options, including an employer statement, pay stubs, or an SSA-44 attestation.
- Form SSA-44 field-by-field walkthrough — the current 12-2025 edition, step by step, with the exact mapping from IRS Form 1040 Line 11 (AGI) and Line 2a (tax-exempt interest) to the form's income estimate fields. Includes worked dollar examples for retirement, widowhood, and pension loss so you can see the arithmetic before you fill in your own numbers.
- Multi-year MAGI estimation worksheet — a printable calculator for projecting income in the tax year selected for Step 2 under SSA's MAGI comparison instructions and in the following year (Step 3) when that year's MAGI is expected to be lower, including partial-year employment income, Social Security benefits, and pension payments. Leaving Step 3 blank means SSA uses your Step 2 estimate for the next year — the guide explains why that matters and when to complete both.
- Dual-spouse coordination log — if you're married and both on Medicare, each spouse seeking a change must make a separate request to SSA. Form SSA-44 is one way to request it, but the form is optional. The log keeps both requests consistent and both submissions tracked.
- Post-submission tracking and refund guide — what to expect after you file, how SSA processes the request, how Part B refunds or direct-bill overpayments are handled, and what happens when SSA later compares your estimate to your actual tax return. Includes what to do if the estimate turns out low and when to escalate to formal reconsideration (Form SSA-561-U2).
- Filing route comparison — online upload through my Social Security, mail, fax, phone intake, and in-person field office visit, with practical notes on turnaround and documentation for each.
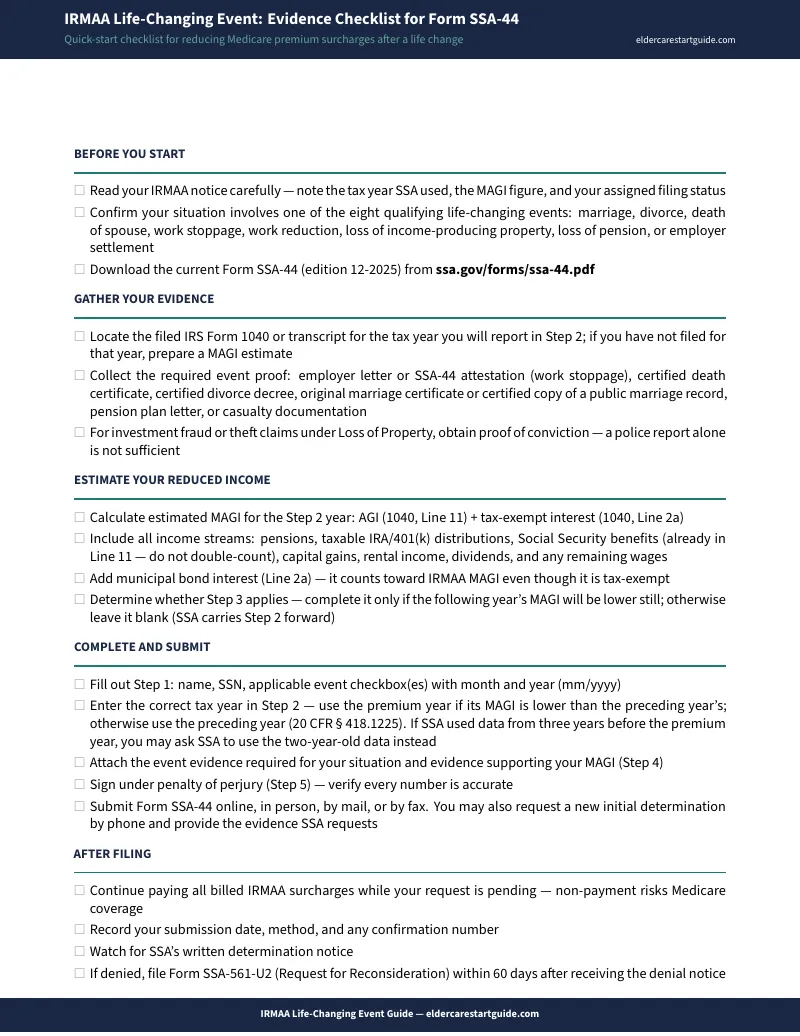
Plus the IRMAA Evidence Checklist — a printable two-page reference listing every qualifying event, the primary evidence for each, and the filing steps, designed to sit next to the form while you work through it. Available as a free download.
Who this is built for
If you just retired and your premiums doubled — your 2024 tax return showed a full year of employment income. Now you're living on a pension and Social Security, but Medicare is using the old number. Work stoppage is a qualifying life-changing event, and the guide walks you through the retirement filing from evidence gathering to income estimation.
If your spouse died and the surcharge went up — after a spouse's death, the surviving partner's IRMAA bracket thresholds shift: a joint return's threshold is $218,000, but a single filer's is $109,000. The same household income can push a surviving spouse into a higher tier. Death of a spouse is a qualifying event, and the guide covers the evidence, the bracket transition, and the income projection for the year of death and the year after.
If you're the adult child helping a parent navigate the notice — your parent may not understand what IRMAA is, may not have a my Social Security account, and may not know where their 2024 return is filed. The guide is written so you can walk through it together — but it's clear about the legal boundary: the beneficiary or their SSA-appointed representative payee may request the determination; a power of attorney alone does not make a family helper SSA's representative.
If your pension was cut, your property income disappeared, or your employer paid a settlement — the eligibility rules are specific. A pension loss must involve a traditional defined-benefit or cash-balance plan; qualifying reasons include plan failure or termination, scheduled cessation, or a spouse's death with no or reduced survivor benefits. A property loss must involve income-producing property lost beyond your control; an employer settlement must result from the employer's closure, bankruptcy, or reorganization. The guide breaks out each event with its own checklist.
Why free resources aren't enough
Form SSA-44 is free. SHIP counselors provide free, unbiased help (find yours at shiphelp.org). The Medicare Rights Center helpline is free (1-800-333-4114). Those resources are real, and you should know they exist — this guide says so on the first page.
What free resources don't give you is a structured filing workflow. The SSA website explains that Form SSA-44 exists; it doesn't walk you through what happens when you need to estimate partial-year income after a mid-year retirement, or when your employer closed and no one can produce the work-stoppage letter, or when both spouses need to make separate requests based on the same joint return. SHIP counselors give excellent advice — but they can't organize your evidence, fill in your estimate, or coordinate dual-spouse requests for you. Insurance broker websites publish articles about IRMAA; they're lead-capture funnels engineered to harvest your contact information for Medicare Advantage sales.
This guide is what sits between "I know what Form SSA-44 is" and "I've filed a complete, correct request with the right evidence the first time." It's a purchase of organized execution, not of information you can't find elsewhere.
Important notice
This is an independent educational guide. It is not affiliated with, endorsed by, or connected to the Social Security Administration, the Centers for Medicare & Medicaid Services, the Department of Health and Human Services, or any other government agency. Form SSA-44 and all associated services are available free of charge directly from SSA at ssa.gov or by calling 1-800-772-1213. This guide provides organizational frameworks, worksheets, and educational commentary to help you prepare your own filing.
Satisfaction guarantee
If the guide doesn't help you organize your IRMAA filing, email [email protected] and we'll refund your purchase — full refund, no time limit.
Get the free checklist or the full guide
The free IRMAA Life-Changing Event Evidence Checklist covers the qualifying events, the evidence for each, and the filing steps — a solid starting point if you want to confirm your event qualifies before committing to anything.
The full guide adds the Form SSA-44 field-by-field walkthrough, the MAGI estimation worksheet, the dual-spouse submission tracker, the evidence matrix, the post-submission timeline log, the 2026 bracket reference, the agency communication log, and work-stoppage evidence guidance — 8 PDFs in total, everything you need to file a complete request on your own.
Frequently Asked Questions
What if the rules change after I buy?
We update the guide when the rules change. Email us any time, even years later, and we'll send you the current edition free.